Mathematical Modeling of Risk Distribution Across Diverse Electronic Betting Formats in Licensed Digital Spaces
Ulrich Hayes · Jul 12, 2026
Mathematical Modeling of Risk Distribution Across Diverse Electronic Betting Formats in Licensed Digital Spaces
Mathematical models form the backbone of risk assessment in electronic betting environments where operators manage exposure across multiple formats simultaneously. Researchers apply frameworks drawn from probability theory and stochastic processes to quantify potential losses and allocate capital reserves accordingly. These approaches allow platforms to maintain stability while handling wagers on sports outcomes, card games, and virtual events within regulated digital networks. Core techniques include Monte Carlo simulations that generate thousands of outcome scenarios based on historical data distributions. Analysts input parameters such as payout structures and participation rates to produce estimates of tail risks that exceed standard deviation measures. Value-at-risk calculations then translate these outputs into capital requirements that satisfy licensing conditions set by oversight bodies.Key Frameworks in Current Use
Poisson distributions model the arrival rates of betting events in high-volume formats where outcomes occur independently over fixed intervals. This method proves effective for projecting aggregate exposure in real-time markets that update continuously throughout events. Variance-covariance matrices extend the analysis by capturing correlations between different betting categories, revealing how a shift in one market segment influences others.
Studies conducted through academic partnerships in 2025 demonstrated that hybrid models combining extreme value theory with machine learning refinements improve accuracy for rare-event forecasting. Regulators in several jurisdictions now require operators to submit model validation reports at regular intervals to confirm ongoing reliability.
Cross-Format Risk Allocation
Electronic platforms often operate fixed-odds, spread, and parimutuel structures side by side. Each format carries distinct risk profiles that models must integrate into unified dashboards. Fixed-odds systems expose operators to direct liability per wager, while parimutuel pools shift much of the variance to participants through shared payouts.
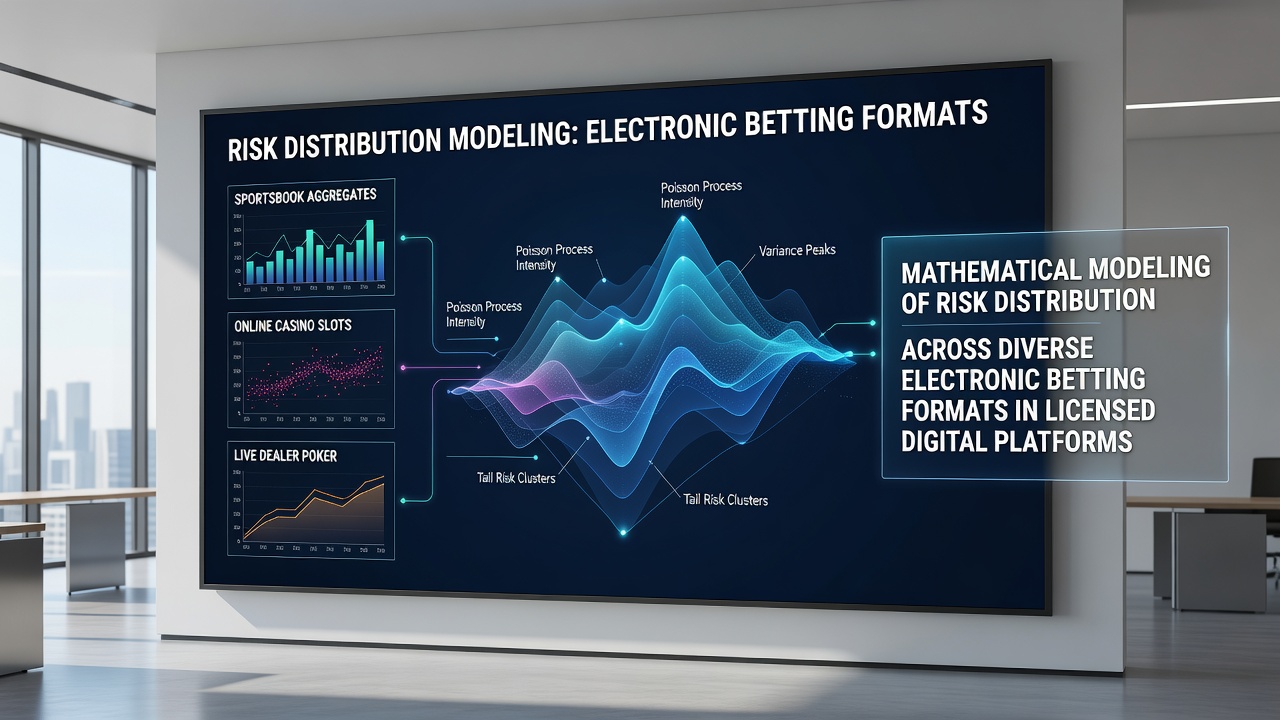
Dynamic hedging strategies rely on real-time recalibration of these models as new information arrives. Operators adjust reserve levels according to updated correlation estimates, preventing isolated market movements from cascading through the entire portfolio. Data collected from North American and European exchanges shows that platforms employing continuous simulation updates experienced lower drawdown frequencies during volatile periods in early 2026.
Regulatory and Technical Integration
Licensed digital spaces require transparent documentation of model assumptions and stress-testing protocols. Agencies such as the Malta Gaming Authority and the New Jersey Division of Gaming Enforcement mandate periodic audits that examine both input data quality and algorithmic robustness. External reviewers compare model outputs against actual loss distributions to identify drift or parameter instability.
July 2026 saw the rollout of enhanced reporting standards across several multi-jurisdictional operators that standardized risk metric definitions for easier cross-border comparison. These updates incorporated feedback from quantitative research groups focused on heavy-tailed return distributions common in betting environments.
Emerging Developments and Limitations
Advances in quantum computing simulations promise faster processing of high-dimensional risk surfaces, yet current implementations remain constrained by data latency issues. Researchers continue to refine copula functions that better represent joint tail dependencies between seemingly unrelated betting categories.
Limitations persist around black-swan scenarios where historical data provides insufficient coverage. Models therefore incorporate scenario analysis drawn from synthetic data generation techniques to explore plausible extremes outside recorded experience. Industry reports from organizations like the European Gaming and Betting Association highlight ongoing efforts to standardize these supplementary tests.
Conclusion
Mathematical modeling of risk distribution supplies licensed operators with quantitative tools to navigate exposure across electronic betting formats. Continued refinement through academic-industry collaboration and regulatory feedback supports more resilient system design. As digital spaces evolve, these frameworks adapt to incorporate new data streams and computational methods while preserving core principles of probabilistic forecasting and capital allocation.